

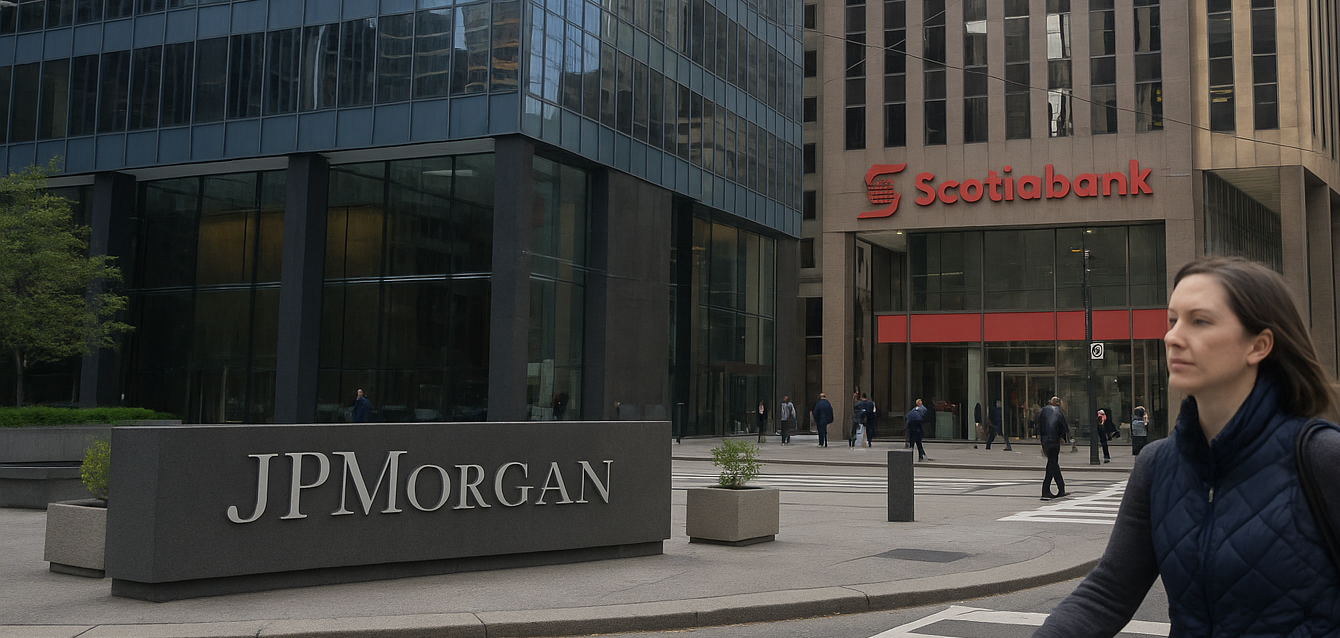
When a global bank starts hiring senior talent to build out a bigger Canadian footprint, it’s not just Bay Street gossip. JPMorgan’s move to bring in the former leader of Scotiabank’s innovation-focused banking team is a sign that big money sees Canada’s tech and growth economy as worth deeper investment. For homeowners, that matters because business lending, job growth, and confidence have a way of showing up later in home prices, sales activity, and mortgage demand. If you’re watching borrowing costs closely this year, it’s also a good time to keep an eye on Best Mortgage Rates as lenders jockey for market share.
Why a U.S. banking giant cares about Canada’s innovation market
Canada often gets described as “steady,” but our innovation hubs are anything but quiet. Toronto-Waterloo, Vancouver, Montréal, Calgary, and Ottawa keep attracting venture capital, talent, and new companies. When a player like JPMorgan invests in leadership to expand here, it’s typically because they expect deal flow—more fundraising, more mergers, more cross-border growth.
From a mortgage broker’s angle, the connection is pretty direct. Stronger business activity supports employment, and employment supports housing demand. Most homeowners don’t buy based on bank hiring headlines, but the labour market does influence whether people upgrade, relocate, or enter the market for the first time.
It’s also worth noting how “innovation banking” differs from traditional commercial banking. These teams specialize in companies with fast growth, complex equity structures, and less predictable cash flow. That takes specialized underwriting, and it tends to cluster in the same cities where housing already feels expensive and competitive.
In other words: when capital gets more available to growth firms, the benefits and pressures tend to concentrate geographically. That can mean more high-income households competing for the same limited housing stock in certain neighbourhoods.
What this could mean for home prices and resale markets
Canadian housing demand doesn’t rise and fall on one factor. It’s a mix of rates, immigration, job stability, investor activity, and plain old supply constraints. But business expansion can be a quiet accelerant, especially in tech-heavy regions where salaries can jump quickly.
Nationally, sales activity is tracked closely by the Canadian Real Estate Association. CREA’s monthly statistics are one of the better snapshots of how buyers are reacting in real time—price trends, new listings, and actual transaction volume. If you like following the numbers, CREA posts the latest updates here: https://www.crea.ca/housing-market-stats/.
Here’s the part homeowners sometimes miss: even if you’re not planning to move, stronger sales in your area can influence your refinancing options later. Higher comparable values can improve loan-to-value ratios, which sometimes opens better pricing or more flexibility—assuming your income and credit qualify.
On the supply side, the long-running issue is that construction hasn’t kept up with household formation in many markets. CMHC has been blunt about the gap between what’s being built and what’s needed. Their housing supply and affordability research is worth a read, especially if you’re trying to understand why prices feel “sticky” even when rates rise: https://www.cmhc-schl.gc.ca/.
So if more business investment boosts local hiring while housing completions lag, you can get a familiar Canadian outcome: demand presses up against limited supply. That doesn’t guarantee a price surge, but it can keep a floor under prices in the hottest employment centres.
Rates still run the show—and the Bank of Canada isn’t done shaping demand
Even with positive business news, mortgage affordability still hinges on the Bank of Canada’s policy rate. Over the last couple of years, we’ve all seen how quickly payments can jump when borrowing costs rise. That shock changed buyer behaviour, slowed resale activity at times, and pushed more homeowners to think about term strategy.
The Bank of Canada posts policy decisions, statements, and key rate information in one place. If you want to track the source instead of headlines, start here: https://www.bankofcanada.ca/core-functions/monetary-policy/key-interest-rate/.
In my day-to-day work, the most common question is whether to lock in or ride it out. There’s no universal answer, but the choice often comes down to risk tolerance and cash flow. If you’re comparing structures, it helps to understand how a Fixed Rate behaves versus a variable option when markets get choppy.
One trend I’m watching: when confidence returns—because jobs look strong and credit is flowing—buyers tend to re-enter quickly once rates stop rising. That “snap back” can happen before affordability truly improves. It’s why calm rate periods often bring sudden competition, especially for family homes in good school zones.
For homeowners renewing in the next 6–18 months, this business expansion news is less about immediate rate changes and more about the economic backdrop. A stronger growth outlook can keep inflation risks alive, which is part of what central banks watch. That’s not a prediction—just the reality of how the chessboard is set.
What homeowners can do now: plan for flexibility, not perfection
If you’re in the 30–55 age range, you’re often juggling the biggest financial load: mortgage, childcare, car payments, maybe aging parents, and maybe a renovation. The goal isn’t to “time” the market perfectly. It’s to avoid getting boxed in by your mortgage terms.
That’s where strategy matters: prepayment privileges, portability, and penalty language can matter as much as the rate itself. If you’re considering a move, a separation, a job change, or even a big renovation, those clauses can cost (or save) thousands later.
And if you’re looking at using home equity for renovations or other goals, it’s smart to compare products rather than defaulting to whatever your bank offers at renewal. A HELOC can be useful for flexibility, but it needs a plan, because the payment structure is different than a standard mortgage.
One more practical note: lenders are competitive when they believe borrowers have options. Big banks expanding in Canada can add to that competition over time, especially for strong credit profiles and stable incomes. That doesn’t mean everyone gets a deal—but it does mean shopping around often pays off.
If you’re unsure what a rate change means in dollars, run the numbers first and stress-test your budget. Even small differences add up over a five-year term when you apply them to a large balance. A quick check with a Mortgage Calculator can help you understand your real monthly exposure before you commit to a term.
Conclusion: follow the money, but manage your own risk
JPMorgan’s decision to build out Canadian operations with leadership from a major domestic bank is a reminder that global capital is still interested in Canada’s growth sectors. Over time, more investment and hiring can support housing demand—especially in innovation-heavy cities—while supply remains the hard constraint.
Still, rates and mortgage terms will drive your personal outcome far more than any single corporate move. If you’re renewing, buying, or restructuring debt this year, it’s worth getting a second set of eyes on your options. If you want help comparing terms and building a plan that fits your budget, the Unrate.ca team can walk you through it without the pressure.
Leave a Reply